Start with three things to look for
- The direction
Above zero means a gain. Below zero means a loss. A negative year is not the same thing as losing everything.
- The period
A good year can sit inside a rough decade. Always check the start and end dates.
- The dollars
A 10% decline means $1,000 on $10,000, but $10,000 on $100,000. Think about the money you would actually need.
The data below cover 2000–2025, not the unfinished 2026 calendar year. They come from an academic U.S. historical-return dataset maintained by Aswath Damodaran at NYU Stern. The stock series includes dividends. It is not a particular fund’s actual return.
Follow a hypothetical $10,000 over time
Start at the left edge, where each line begins with the same amount. Follow a line to the right to see how reinvested returns change the ending balance. Switch periods to test whether your first impression depends on the starting date.
The “60/40” line mixes 60% stocks with 40% 10-year Treasuries. The Treasury-bill line uses the source’s average short-term rate as a cash-like proxy, not a bank savings account. These are no-cost historical calculations without contributions or withdrawals.
Starts at $10,000. Lines connect year-end observations. Switch periods to see how the starting date changes the story.
A smooth-looking line can hide a stressful year. These charts connect year-end points; they do not show every move between them.
Want more detail? Compare growth and bumpiness
The chart below adds a more technical idea: volatility, or how widely yearly returns varied. Farther right means more variation in this historical sample. Higher up means a higher compound annual growth rate for the whole period.
Compound annual growth rate, often shortened to CAGR, is the steady annual rate that would produce the same final result. It does not mean that return happened every year. You can skip the formula and still understand the main point: return and the experience of getting there are different things.
Growth and bumpiness are different questions
How to read it: Higher means more annualized growth; farther right means yearly returns varied more in this sample.
What it means for you: This describes one historical period. It is not a menu of promised returns or an optimized portfolio.
Go deeper: numbers, assumptions, and source
| Series | Yearly variation | Annualized growth |
|---|---|---|
| Stocks | 17.79% | 8.00% |
| Treasuries | 8.78% | 3.82% |
| T-bill proxy | 1.98% | 1.93% |
| Baa bonds | 7.26% | 6.30% |
| Gold | 17.93% | 10.96% |
| 60/40 | 9.95% | 6.94% |
NYU Stern / Damodaran, 2000–2025, nominal U.S. dollars. Hypothetical mixes reset annually, reinvest returns, and exclude fees, taxes, and cash flows. Not fund performance. Variation uses the sample standard deviation of 26 annual returns, with n−1 in the denominator.
The full year-by-year record
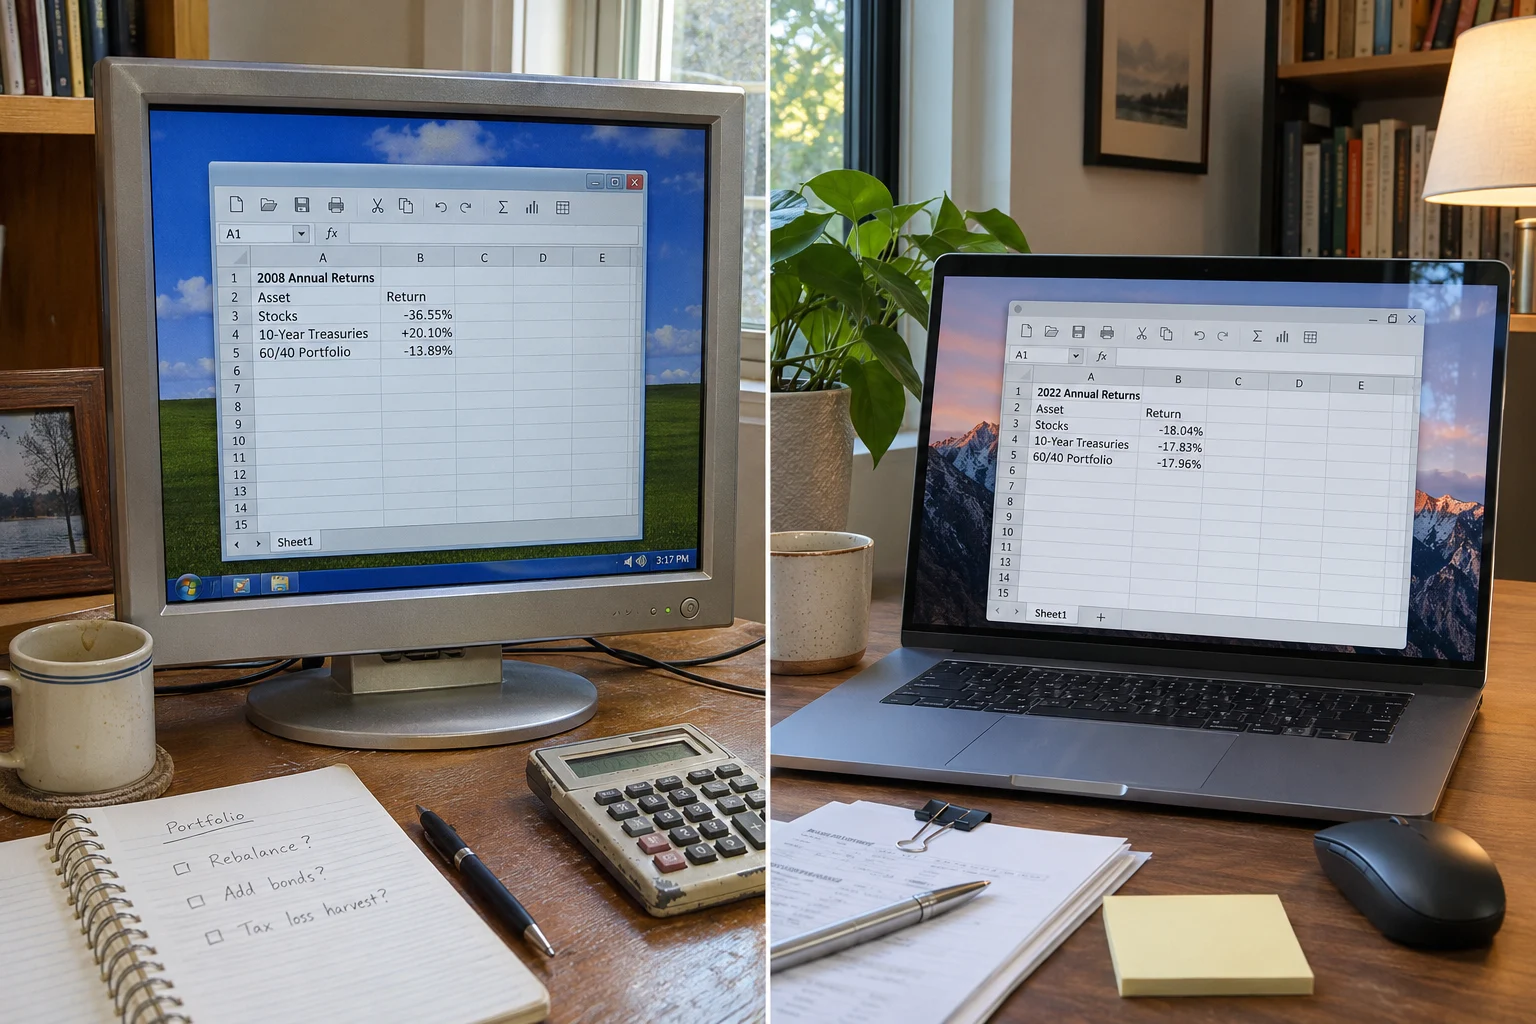
2008
Stocks and bonds diverged
2022
Stocks and bonds both fell
Use this table when you want to check an exact number. Choose one year and compare across; then follow one column down to see how much an investment’s experience changed. The three mix columns are calculated examples, not products for sale.
| Year | Stocks + dividends | 10-year Treasuries | T-bill proxy | Baa corporate bonds | Gold | 30/70* | 60/40* | 80/20* |
|---|---|---|---|---|---|---|---|---|
| 2000 | -9.03% | +16.66% | +6.00% | +9.38% | -5.44% | +8.95% | +1.25% | -3.89% |
| 2001 | -11.85% | +5.57% | +3.48% | +8.60% | +0.75% | +0.34% | -4.88% | -8.37% |
| 2002 | -21.97% | +15.12% | +1.64% | +12.06% | +25.57% | +3.99% | -7.13% | -14.55% |
| 2003 | +28.36% | +0.38% | +1.03% | +12.38% | +19.89% | +8.77% | +17.17% | +22.76% |
| 2004 | +10.74% | +4.49% | +1.40% | +10.33% | +4.65% | +6.37% | +8.24% | +9.49% |
| 2005 | +4.83% | +2.87% | +3.22% | +5.13% | +17.77% | +3.46% | +4.05% | +4.44% |
| 2006 | +15.61% | +1.96% | +4.85% | +5.27% | +23.20% | +6.05% | +10.15% | +12.88% |
| 2007 | +5.48% | +10.21% | +4.48% | +4.90% | +31.92% | +8.79% | +7.37% | +6.43% |
| 2008 | -36.55% | +20.10% | +1.40% | -3.44% | +4.32% | +3.11% | -13.89% | -25.22% |
| 2009 | +25.94% | -11.12% | +0.15% | +19.96% | +25.04% | -0.00% | +11.12% | +18.53% |
| 2010 | +14.82% | +8.46% | +0.14% | +9.40% | +29.24% | +10.37% | +12.28% | +13.55% |
| 2011 | +2.10% | +16.04% | +0.05% | +12.26% | +12.02% | +11.86% | +7.68% | +4.89% |
| 2012 | +15.89% | +2.97% | +0.09% | +9.40% | +5.68% | +6.85% | +10.72% | +13.31% |
| 2013 | +32.15% | -9.10% | +0.06% | -1.13% | -27.61% | +3.28% | +15.65% | +23.90% |
| 2014 | +13.52% | +10.75% | +0.03% | +10.75% | +0.12% | +11.58% | +12.41% | +12.97% |
| 2015 | +1.38% | +1.28% | +0.05% | -1.50% | -12.11% | +1.31% | +1.34% | +1.36% |
| 2016 | +11.77% | +0.69% | +0.32% | +11.52% | +8.10% | +4.01% | +7.34% | +9.55% |
| 2017 | +21.61% | +2.80% | +0.95% | +9.15% | +12.66% | +8.44% | +14.09% | +17.85% |
| 2018 | -4.23% | -0.02% | +1.97% | -3.18% | -0.93% | -1.28% | -2.55% | -3.39% |
| 2019 | +31.21% | +9.64% | +2.11% | +15.25% | +19.08% | +16.11% | +22.58% | +26.90% |
| 2020 | +18.02% | +11.33% | +0.36% | +10.60% | +24.17% | +13.34% | +15.34% | +16.68% |
| 2021 | +28.47% | -4.42% | +0.04% | +1.02% | -3.75% | +5.45% | +15.31% | +21.89% |
| 2022 | -18.04% | -17.83% | +2.09% | -15.23% | +0.55% | -17.89% | -17.96% | -18.00% |
| 2023 | +26.06% | +3.88% | +5.28% | +8.74% | +13.26% | +10.53% | +17.19% | +21.62% |
| 2024 | +24.88% | -1.64% | +5.18% | +1.74% | +25.96% | +6.32% | +14.27% | +19.58% |
| 2025 | +17.78% | +7.80% | +4.21% | +6.96% | +66.22% | +10.79% | +13.79% | +15.78% |
Download the data and calculations (CSV) ↓
*Stock / 10-year Treasury mixes, reset annually. Dollar returns, before fees and taxes.
Why the same dollars buy less over time
Inflation means prices rise. You can have exactly the same number of dollars in your account and still be able to buy less. The lines below show the cost of a fixed shopping basket and what a hypothetical, non-interest-bearing $10,000 can buy.
A grocery budget, not a disappearing balance
If the things you bought for $100 later cost $110, your $100 did not vanish. It simply covers less of the same shopping list. Your household’s experience may differ from a national average.
This chart uses the U.S. CPI-U, a broad consumer-price measure, for 2015–2024. The amounts compare annual-average price levels. They are not exact start-to-end investment returns adjusted for inflation.
Same cash balance. Less buying power.
How to read it: Blue is the basket’s price in each year. Purple is $10,000 without interest. Gold is that cash measured in 2015 buying power.
What it means for you: Cash can meet an important short-term need even while prices erode its long-term buying power.
Go deeper: numbers, assumptions, and source
| Year | Basket cost | Unchanged cash | Buying power |
|---|---|---|---|
| 2015 | $10,000 | $10,000 | $10,000 |
| 2016 | $10,126 | $10,000 | $9,875 |
| 2017 | $10,342 | $10,000 | $9,669 |
| 2018 | $10,594 | $10,000 | $9,439 |
| 2019 | $10,786 | $10,000 | $9,271 |
| 2020 | $10,920 | $10,000 | $9,158 |
| 2021 | $11,433 | $10,000 | $8,747 |
| 2022 | $12,347 | $10,000 | $8,099 |
| 2023 | $12,856 | $10,000 | $7,779 |
| 2024 | $13,235 | $10,000 | $7,556 |
BLS annual-average CPI-U, 2015–2024. Different price bases are identified in the legend. Not an exact start-to-end real investment return.
How the numbers were built
All investment returns are nominal U.S. dollar figures: they have not been adjusted for inflation or taxes. Stocks use the source’s S&P 500 series including dividends; Treasuries use its 10-year bond returns; corporate bonds use its Baa series; gold uses its gold price-return series. The 3-month Treasury-bill column is the source’s annual-average-rate proxy.
Hypothetical mixes reset at the start of each year, reinvest returns, and assume no costs, taxes, new deposits, or withdrawals. Calculations use source values rounded to two decimals, so results are approximate. Year-end drawdowns can miss much deeper losses within a year.
Different data sources, bond choices, start dates, and fees can produce different results. Past U.S. performance is not a forecast for other countries or for the future. Detailed data remain downloadable so you can check the arithmetic.
Questions readers ask next
A few practical questions related to this guide. Browse all 36 questions →
Sources & editorial notes
- Investor.gov: asset allocation and diversification
- CFPB: building an emergency fund
- FDIC: what deposit insurance covers
- Investor.gov: index funds
- NYU Stern / Damodaran historical U.S. returns
- BLS annual-average CPI-U
Historical sources were checked Nov 4, 2026; beginner education sources Nov 5, 2026. All people and personal-money examples are fictional. Charts distinguish historical data from hypothetical calculations.
AI-assisted educational content, not yet reviewed by a licensed financial professional. This is general information, not a personalized investment recommendation. Investment losses are possible. Product, account, and tax rules should be checked for your circumstances.